How to Calculate a Real Interest Rate
Use exact and approximate real interest formulas to adjust nominal rates for inflation and test savings purchasing-power outcomes.
Quick answer: Compute a real interest rate by adjusting a nominal interest rate for inflation. For a one-period comparison use the exact calculation [(1 + nominal rate)/(1 + inflation rate) − 1] × 100%. Nominal minus inflation is a useful approximation, particularly when both percentages are modest.
What you will achieve: You will distinguish how much a balance grows in nominal currency from how much its purchasing power changes. The result depends on which inflation rate you use and is not a promise about future savings or borrowing costs.
Before you begin
Write down a nominal interest rate and the inflation rate for the same time interval and region. Convert percentage inputs into decimals for the exact formula: 5% = 0.05. Determine whether the interest figure is an effective annual yield, a stated nominal APR, a post-tax return or something else. Match effective rates over comparable periods.
Use the exact relation (1 + nominal rate) ÷ (1 + inflation rate) − 1 when a precise real return is required. Keep the two rates over the same period and distinguish realized inflation from forecasts.
Step-by-step instructions
Step 1: Confirm the rate’s meaning
A savings APY/AER already includes compounding over its stated annual period; a quoted APR can be a different convention. For loans, costs and fees may make the borrower’s actual return/cost differ from the simple rate. Do not substitute a monthly rate into an annual calculation.
Step 2: Choose the relevant price-change measure
For a historical real return, use a realized inflation rate for the same span. For expected real returns, use an expressly labeled inflation assumption or expected rate; actual inflation may differ. Make sure both rates are for the same country or purchasing basket.
Step 3: Convert the percentages
Write 5% nominal interest as 0.05 and 3% inflation as 0.03. In spreadsheet software use a percentage cell consistently; typing 5 into a cell formatted as 5% may produce a 500% error depending on how the formula is built.
Step 4: Calculate the nominal growth factor
For a $1 starting unit, the nominal one-period value at 5% is 1.05 units. The price level at 3% inflation rises by a factor of 1.03. Dividing the two factors directly compares the grown cash balance with the cost of the indexed basket.
Step 5: Compute the exact real rate
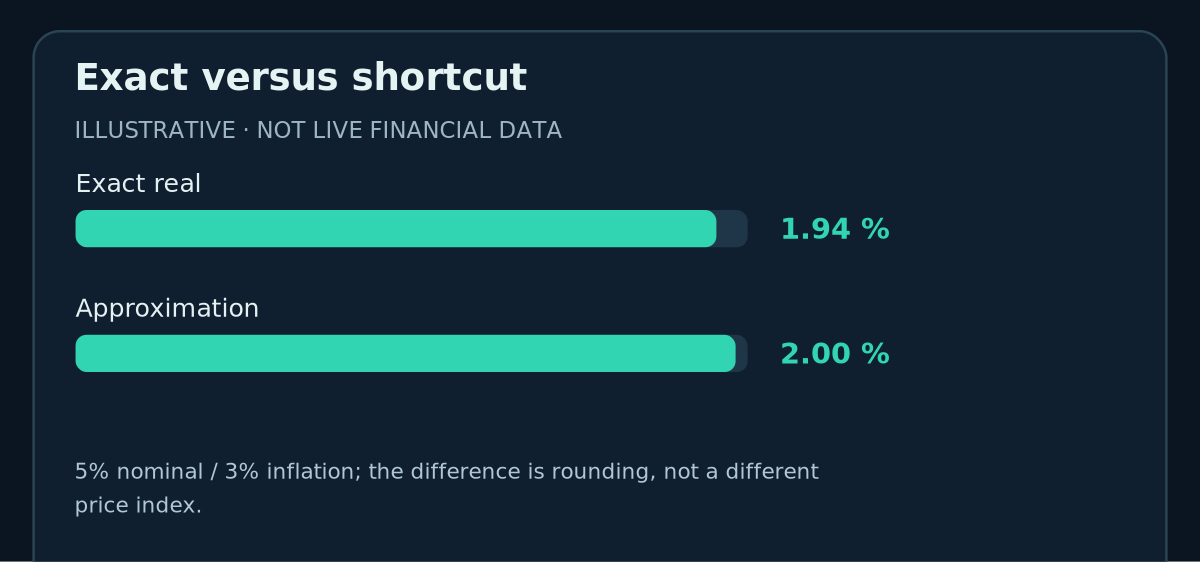
Perform 1.05/1.03 − 1 = about 0.0194175. Multiply by 100 to report 1.94% to two decimal places. The nominal-minus-inflation shortcut gives 2.00%, an approximate rather than exact answer.
Step 6: Apply it to your starting balance
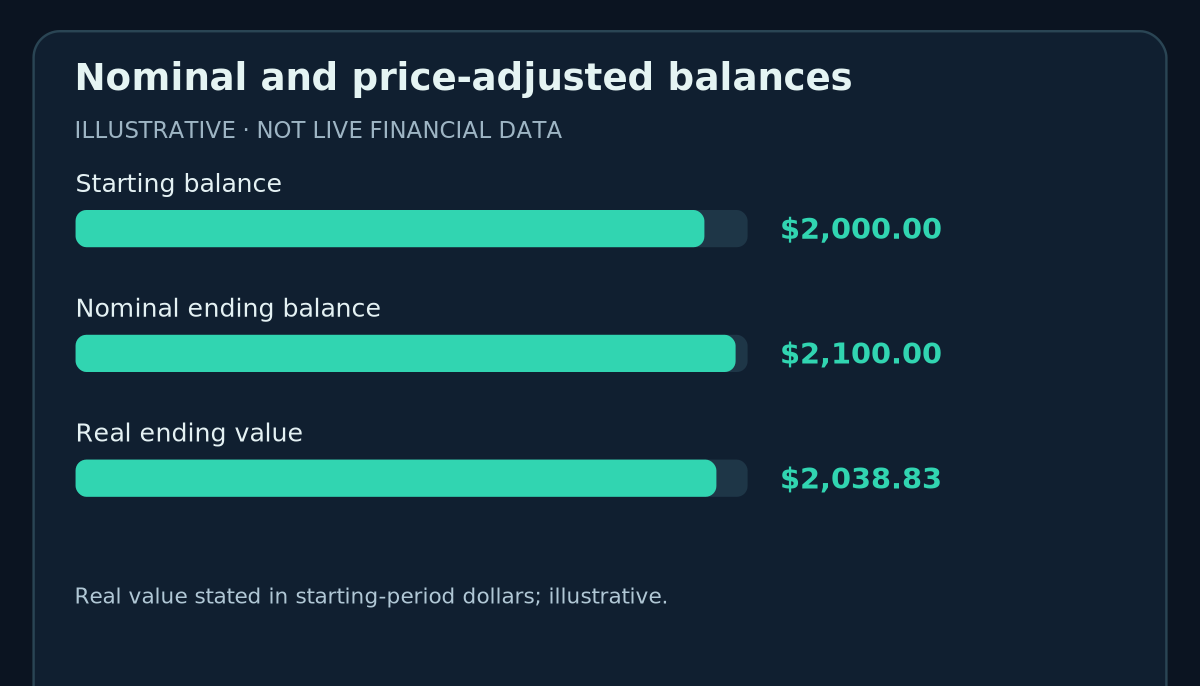
If the starting balance is $2,000 and earns 5% over one year, the nominal ending amount is $2,100. To express it in starting-period dollars, divide $2,100 by 1.03; the real value is about $2,038.83. The purchasing-power gain is roughly $38.83.
Step 7: Check for negative or unusual results
A 2% nominal annual yield with 5% inflation gives (1.02/1.05 − 1) × 100 ≈ −2.86%. Your money balance can increase while its indexed purchasing power declines. Record results with a plus or minus sign.
Step 8: Separate fees and taxes
For an after-tax calculation use the actual after-tax growth factor, then divide by inflation factor. Do not invent a tax rate and assume it applies worldwide. Keep product fees and inflation separate in your worksheet.
Formula and assumptions
Exact one-period real rate = (1 + i)/(1 + π) − 1, where i is the nominal effective rate and π is the inflation rate as decimals. Approximate real rate ≈ i − π. Require 1 + π > 0.
Fully worked example
Educational assumptions: effective annual nominal growth 5%, annual inflation 3%, starting savings $2,000, no tax, no fees. Nominal ending balance = $2,000 × 1.05 = $2,100.00. Real ending value in starting-year dollars = $2,100/1.03 = $2,038.83. Exact real rate = 1.05/1.03 − 1 = 1.94%.
Second scenario and interpretation
At illustrative 2% nominal growth with 5% inflation, the exact real result is −2.86%. The subtraction shortcut gives −3%, which is close but not identical. Neither 2%, 3%, nor 5% represents a claimed current bank offer or published inflation outcome.
Common mistakes and troubleshooting
Subtracting when an exact answer is needed
Use the ratio of growth factors for precise annual comparisons.
Comparing an APR with an APY without conversion
Match compounding conventions, time periods and fee assumptions.
Using future inflation as an established fact
Future inflation is unknown; clearly label scenarios.
Ignoring deposit fees and taxes
Your actual after-fee, after-tax rate may differ materially.
Alternatives and special cases
Savings account
Use disclosed effective yield over the comparison period; then adjust for realized or assumed inflation.
Fixed-rate debt
Calculate the borrowing rate’s purchasing-power burden but still plan for actual nominal payments.
Multi-year horizon
Compute cumulative nominal and price growth factors separately; do not add simple annual percentages blindly.
Differences by country
United States
Federal Reserve educational materials describe nominal-minus-inflation as a useful approximation. Use a consistent US price index for realized purchasing power.
United Kingdom
APY/AER and APR have different product definitions; compare like-for-like effective periods and your intended UK inflation index.
Canada
Use Canadian inflation for Canadian-dollar purchasing power and verify whether the quoted lending/savings rate is effective or nominal.
Australia
Savings, loans and fees vary by product; inflation adjustment alone is not a contract rate or a tax calculation.
This how to calculate a real interest rate procedure is general education. Confirm current official rules and product or employment details where relevant.
Frequently asked questions
Is a negative real rate possible when interest is positive?
Yes. Inflation can exceed the cash balance’s nominal growth.
Is the Fisher approximation always accurate?
No. Use (1+i)/(1+π)−1 when the difference matters.
Which inflation figure belongs in next year’s forecast?
A scenario or expectation, explicitly not a known result.
Does a high real savings rate guarantee my buying power?
No. Taxes, fees, uncertain future inflation and spending mix remain relevant.
Final checklist
-
[ ] Identify nominal or effective quote
-
[ ] Use matching time periods
-
[ ] Write rates as decimals
-
[ ] Compute nominal growth factor
-
[ ] Divide by inflation factor
-
[ ] Subtract one and convert to percent
-
[ ] Report inflation and fee assumptions
Sources & Further Reading
-
Federal Reserve Education: Getting Real about Interest Rates — Distinction between nominal and real interest and approximate subtraction. Checked 27 October 2026.
-
Federal Reserve Bank of St. Louis: The Ups and Downs of Inflation and the Role of Fed Credibility — Fisher equation and expected inflation context. Checked 27 October 2026.
-
US Bureau of Labor Statistics: Purchasing power and constant dollars — Price-index ratio and equivalent historical dollar values. Checked 27 October 2026.
Use the checklists as you go, and confirm the result before moving on to a more involved repair.