How to Read a Payslip
Read a payslip line by line: hours, gross pay, payroll deductions, net pay, YTD totals and country-specific rules.
Quick answer: Read a payslip by checking the pay period, hours/rate, gross earnings, itemised deductions, net pay and year-to-date totals. Recalculate pay from recorded hours and compare the net amount against your bank deposit. If a figure seems wrong, request the employer’s payroll explanation rather than guessing why it changed.
What you will achieve: You will be able to audit a typical employee wage statement and prepare a clear correction request. Payslip labels and legal contents differ across countries and employers, so this is a general method rather than a claim that all payslips look alike.
Before you begin
Have the actual payslip from an authorized employer portal, your timesheet, contract or pay agreement, leave and overtime records, bank deposit and previous payslip. Mask tax IDs, addresses, account numbers and other sensitive information before storing or asking anyone else to review documents. This article does not display any fabricated real-bank or employer screenshot.
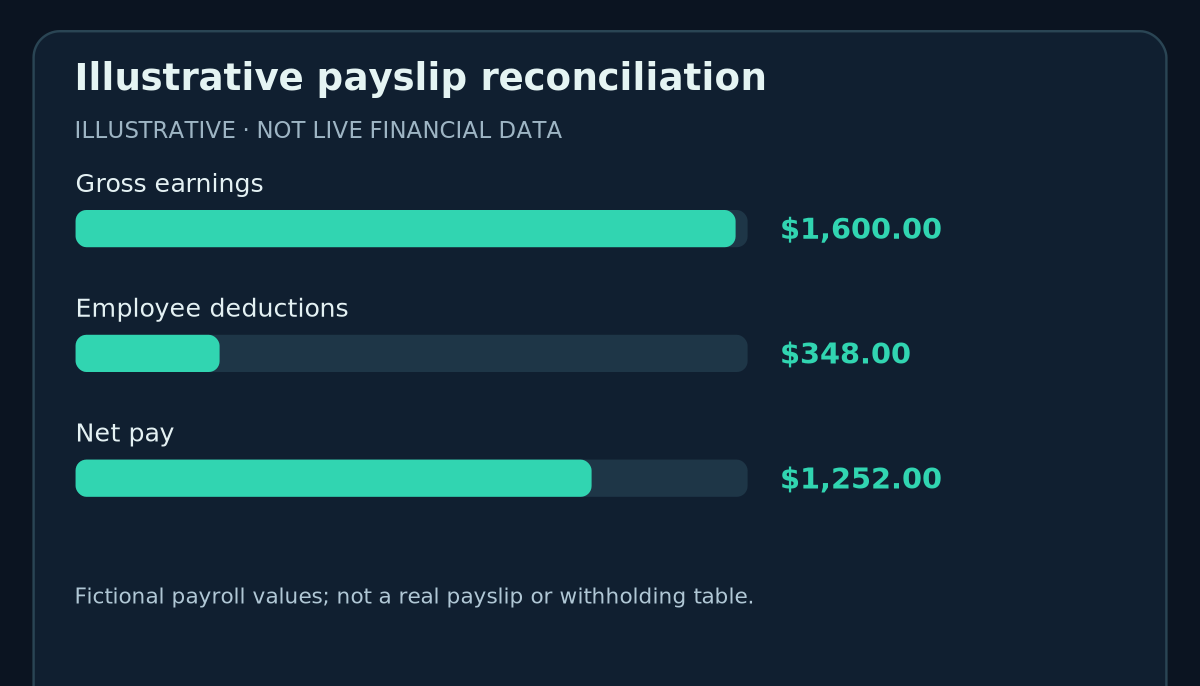
A sample payslip illustrates the reconciliation from gross earnings to net pay, but real deduction names and rates depend on country, payroll period and employment arrangement.
Step-by-step instructions
Step 1: Verify whose pay and which period it covers
Read employee and employer identifiers, start/end dates, pay date and pay frequency. A biweekly slip is not the same as twice-monthly pay. Distinguish the gross earnings period from the bank settlement date, which might differ on holidays.
Step 2: Decode each earnings line
Look for regular hours, rate of pay, overtime, allowances, commissions, paid leave, bonuses and adjustments. If you are on salary, compare agreed periodic salary and any unpaid leave adjustments. A negative earnings line may be a corrected prior period, not necessarily a deduction.
Step 3: Recalculate gross pay
For hourly work, multiply each class of hours by its own pay rate and add legitimate allowances. Do not assume that overtime is always paid at a particular multiplier; eligibility and rates depend on contract and applicable law.
Step 4: Separate statutory and voluntary deductions
Common labels may refer to income tax, national insurance/social contributions, pension contributions, healthcare premiums, dues or repayments. Do not use one country’s payroll terminology as a universal translation. Identify pre-tax versus post-tax deductions where relevant.
Step 5: Reconcile net pay to deductions
Net pay generally equals gross cash earnings minus employee-paid deductions, with adjustments for reimbursed expenses and other item treatments where shown. Record the arithmetic line by line. An employer pension contribution is often informational and is not always cash deducted from the employee’s net pay.
Step 6: Review year-to-date (YTD) separately
YTD earnings and deductions accumulate over a longer period and should not be subtracted as though all were taken this pay period. If an unexpected YTD reset occurs, check fiscal/payroll year and employer transfer conditions.
Step 7: Match your bank deposit
Check the net paid to each account if pay is split among multiple accounts. A single deposit can include an expense reimbursement excluded from taxable earnings. If amounts differ, capture the pay-period identifiers and request an explanation.
Step 8: Escalate an unexplained error
Write to payroll with the pay date, disputed line, hours or contract reference and your calculation. Keep evidence privately. Do not email unredacted identity documents or payroll credentials to an unfamiliar address.
Formula and assumptions
Typical illustrative check: gross earnings − employee deductions + separately paid nontaxable reimbursements = net cash paid, subject to payroll presentation. Each deduction and reimbursement must be classified from the real document, not guessed.
Fully worked example
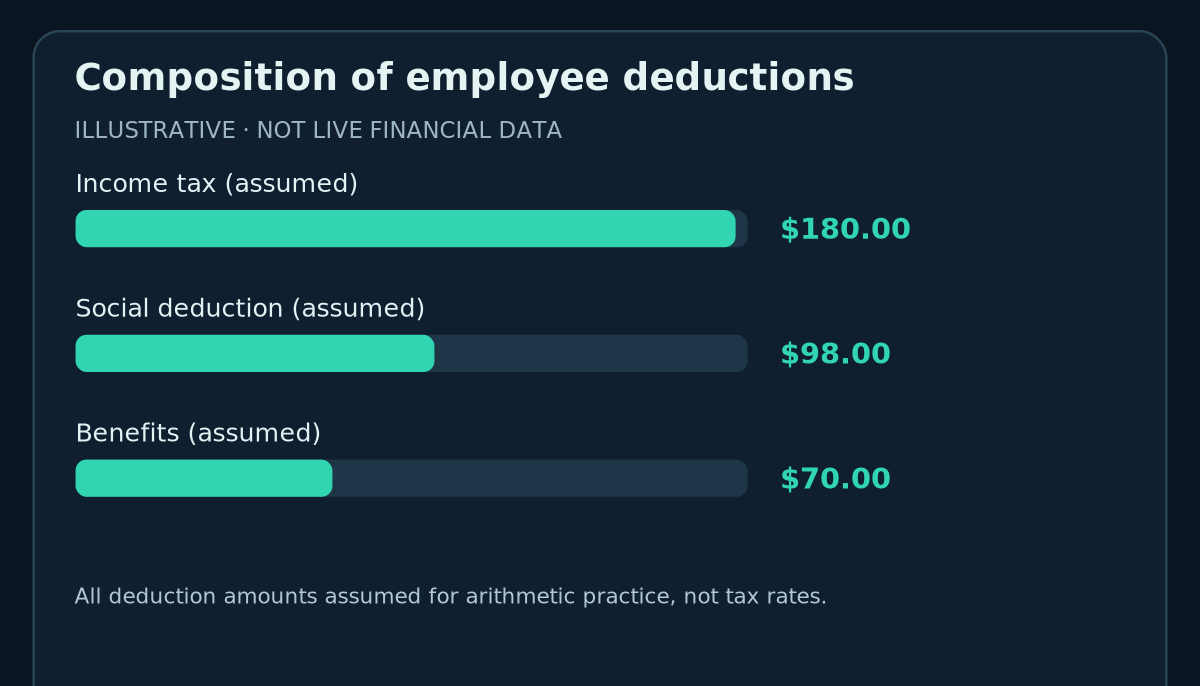
Entirely invented example, not a real employer: 80 regular hours at $20/hour gives $1,600.00 gross. Assume a $180 income-tax deduction, $98 payroll/social contribution and $70 employee benefit deduction, totaling $348.00. Net = 1600 − 348 = $1,252.00. No reimbursement, overtime, employer-side contribution or correction is included.
Second scenario and interpretation
If the bank deposit were hypothetically $1,232 instead of $1,252, the difference would be $20. A legitimate explanation might be another separately recorded employee deduction or account split; do not presume theft or error until the complete stub and bank entries are reconciled. Keep private data out of screenshots posted to public forums.
Common mistakes and troubleshooting
Treating employer contributions as employee deductions
Separate information-only employer amounts from reductions to take-home pay.
Using YTD taxes for one pay period
Pay-period and year-to-date columns have different purposes.
Assuming tax withheld equals final income tax owed
Withholding is a collection mechanism; final liability depends on returns and local tax rules.
Ignoring overtime category or hours
Compare actual approved time records with each earnings row, not just the gross total.
Alternatives and special cases
Salary worker
Check periodic salary, unpaid leave and bonus treatment instead of simply multiplying hours.
Multiple jobs
Read each payroll independently and reconcile each bank deposit; total yearly tax can differ from each employer’s withholding.
Contractor or freelancer
You may receive an invoice/payment advice rather than a statutory employee payslip; do not assume employment-specific deduction or payslip rules apply.
Differences by country
United States
Withholding shown on US employee stubs can include federal/state/local income tax and Social Security/Medicare, with employer-specific benefit lines. Check actual Form W-4 and IRS guidance.
United Kingdom
GOV.UK says employee/worker payslips generally must be provided on or before payday and include pay before/after deductions plus variable deductions; time-worked hours must appear where pay varies by hours.
Canada
FCAC explains gross/net pay, income tax, CPP/QPP and EI deductions; Quebec and other regions can differ.
Australia
Fair Work Ombudsman guidance says employers generally provide payslips within one working day of pay day, with required period, pay, deductions and super contribution details.
This how to read a payslip procedure is general education. Confirm current official rules and product or employment details where relevant.
Frequently asked questions
Can the amount deposited differ from net pay?
Check split deposits, advance recoveries, expense reimbursements and payroll timing before concluding there is an error.
Do YTD deductions come out of my latest pay?
No. YTD normally accumulates earlier pay periods; inspect the current-period column.
Why does a bonus sometimes have different withholding?
Payroll methods and local tax rules can produce different withholding patterns; verify with payroll or relevant tax agency.
What should I do if the payslip is missing?
Ask payroll and consult your jurisdiction’s labor authority; rights differ by employment classification.
Final checklist
-
[ ] Check personal data privately
-
[ ] Match pay period and hours
-
[ ] Recompute every earnings row
-
[ ] List employee deductions
-
[ ] Recalculate net deposit
-
[ ] Check YTD separately
-
[ ] Request written correction for unexplained differences
Sources & Further Reading
-
UK Government: Payslips: employee rights — UK right to itemised payslips, fields and timing. Checked 27 October 2026.
-
Acas: Payslips — UK deductions and hours reported on payslips. Checked 27 October 2026.
-
Australian Fair Work Ombudsman: Pay slips — Australian payslip required details and deadlines. Checked 27 October 2026.
-
Financial Consumer Agency of Canada: Starting your first job — Canada gross pay, net pay, CPP/QPP, EI and income tax deductions. Checked 27 October 2026.
-
US Internal Revenue Service: Tax Withholding — US employee federal tax withholding context, W-4 inputs. Checked 27 October 2026.
Use the checklists as you go, and confirm the result before moving on to a more involved repair.