How to Calculate Your Net Worth
Build a personal net worth statement: total current assets minus outstanding debts, including home equity without double counting.
Quick answer: Calculate your net worth = total current assets − total current liabilities. Assets are the things you own that have a defensible current value; liabilities are the outstanding debts you owe. Make a dated snapshot rather than treating an uncertain future salary as an existing asset.
What you will achieve: You will build a simple financial balance sheet, spot double counting and track progress over time. Net worth is a useful snapshot but not a credit score, cash-flow measure, proof of financial resilience or measure of personal worth.
Before you begin
Bring the latest cash and account balances, investment statements, approximate resale or market values for significant property and vehicles, and all current outstanding loan/card balances. Choose one currency and snapshot date. If an asset is jointly owned, include only a consistent ownership share and the matching portion of related debt; do not double-count a household asset in both people’s statements.
Net worth is a balance-sheet snapshot, not a cash-flow test. Value assets and debts on the same date, and do not count both home equity and the home’s full value without the mortgage liability.
Step-by-step instructions
Step 1: Set a specific valuation date
Record the date and currency of your balance sheet. A stock price, mortgage payoff quote and card balance may change daily. Using statements from different months can create a misleading net figure. Document whether you use market estimates or actual redemption/payoff values.
Step 2: List liquid assets separately
Add available checking/cash, savings and similar balances. Transfers between your own accounts are not additional wealth: count each ending balance once. Pending deposits and uncleared payments should be treated consistently with their associated liabilities.
Step 3: Record investments at current values
Use current statements for stocks, funds and retirement savings, while noting any restrictions, market volatility, exit taxes or penalties separately. Do not substitute cumulative contributions or an optimistic future return for present value.
Step 4: Estimate major physical property conservatively
Include real estate and vehicles at a grounded current resale/market estimate, not original purchase price unless unusually justified. Household clothing, furniture and collectibles are often difficult to value and sell; include them only if reasonably defensible.
Step 5: List each outstanding debt
Include credit card outstanding balances, mortgage principal, vehicle loan, student loan, personal loan and other genuine obligations. A monthly minimum payment is not the total liability. Use the current amount owed rather than the original principal.
Step 6: Subtract the total liabilities
Add asset categories, add debt categories and subtract: assets − liabilities. Do not subtract the mortgage twice if the home appears as a full market value asset. If you list only home equity as an asset, exclude the same mortgage from liabilities to avoid double counting.
Step 7: Distinguish net worth from spendable cash
An asset-rich household can still struggle to pay next month’s bills if most assets are tied up in property or retirement plans. Create a separate cash-flow budget and liquidity buffer; do not interpret a positive net worth as permission to spend.
Step 8: Repeat with a consistent scope
Update every quarter or year using the same inclusion rules and dates. Track the change and explain contributions from loan repayment, market changes, new borrowing and purchases. A temporary decline is not always poor money management.
Formula and assumptions
Net worth = Σ(current asset values) − Σ(current amounts owed). Home equity = current home value − mortgage balance; using home equity rather than gross home value requires changing how the mortgage is counted, not counting both.
Fully worked example
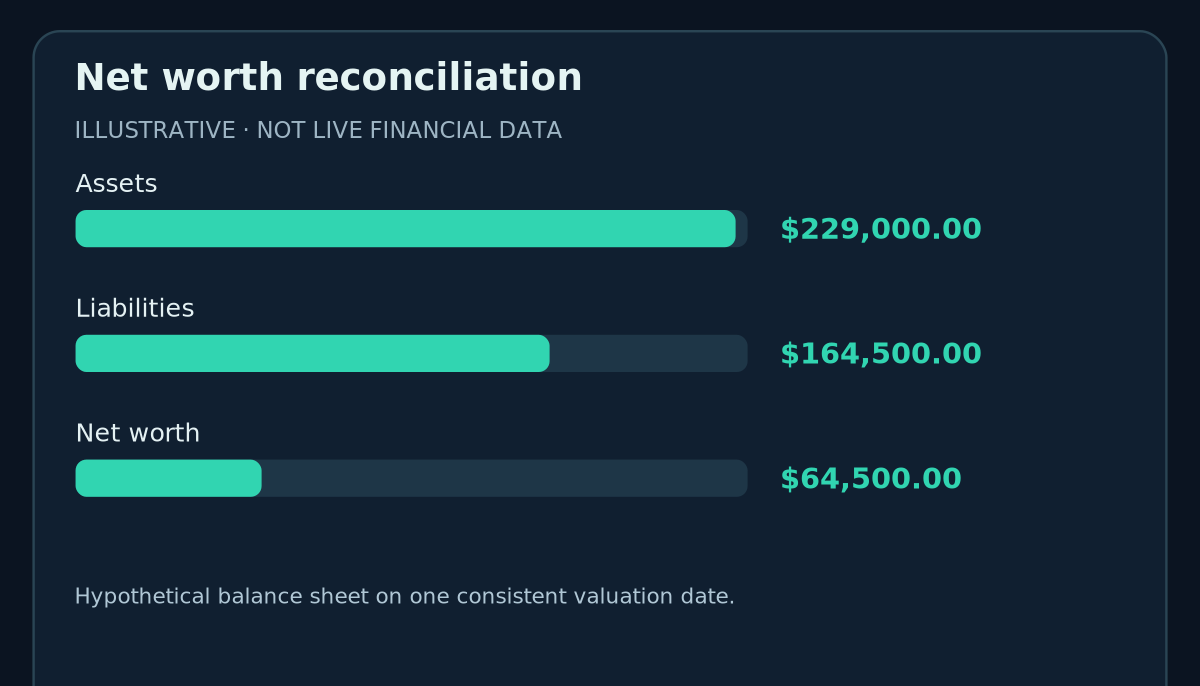
Entirely hypothetical balance sheet: cash $3,500, savings $8,500, investments $25,000, vehicle $12,000 and home $180,000 give assets of $229,000. Mortgage $140,000, vehicle loan $7,000, cards $2,500 and student loan $15,000 total $164,500 in liabilities. Net worth = 229,000 −164,500 = $64,500.
Second scenario and interpretation
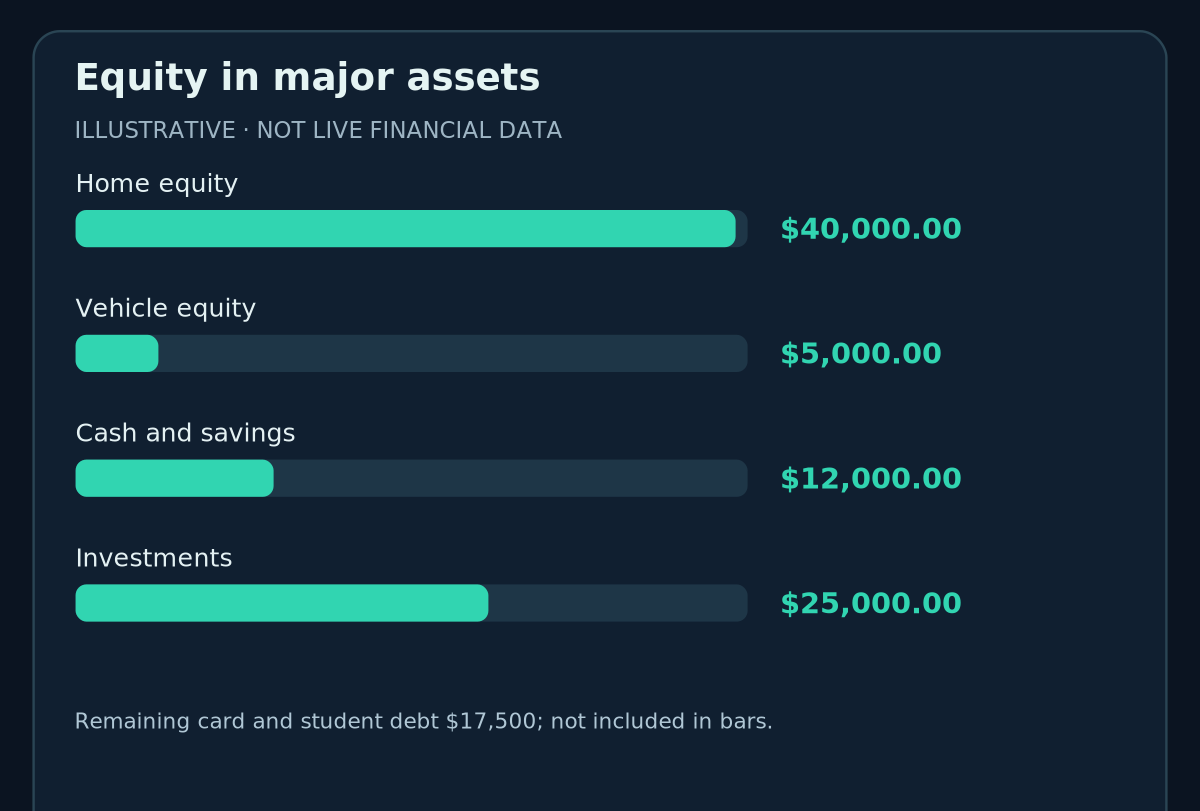
One illustrative decomposition: home equity $180,000−$140,000 = $40,000; vehicle equity $12,000−$7,000 = $5,000; liquid cash and savings $12,000; investments $25,000; remaining unsecured/card and student borrowing $17,500. Sum = $40,000+$5,000+$12,000+$25,000−$17,500 = $64,500. This alternate method must not deduct home and car loans again.
Common mistakes and troubleshooting
Using original purchase cost instead of today’s value
Assets may have depreciated or risen; use a defensible current estimate.
Counting a loan payment instead of loan balance
A $200 minimum payment is not a $200 total debt.
Double counting home equity and mortgage
Either full property value less mortgage, or equity alone without deducting the loan twice.
Leaving out small but high-interest debts
Card balances and overdrafts still reduce net worth.
Equating net worth with immediate liquidity
Home equity and retirement accounts may not fund an urgent cash expense.
Alternatives and special cases
Joint household statement
Use household-owned assets and all corresponding household debts once; agree on a consistent scope.
Individual statement
Allocate ownership interests and joint obligations carefully; a legal or creditor liability share might differ from a simple 50/50 convention.
Foreign assets and liabilities
Convert using exchange rates from one documented snapshot date, and note conversion uncertainty.
Very hard-to-price asset
Use a conservative disclosed estimate or omit it consistently rather than inventing a precise appraisal.
Differences by country
United States
Investor.gov describes a net worth statement as assets less liabilities; mortgage and federal student-loan balances belong in the correct debt category.
United Kingdom
Record pension values and property carefully, but pension access restrictions and UK treatment can differ from liquid savings.
Canada
Use CAD and consistent market values for home and vehicles; debt and property ownership may be shared.
Australia
ASIC Moneysmart’s net worth calculator separates assets and debts; super balances can appear in a wealth snapshot but may not be readily accessible as cash.
This how to calculate your net worth procedure is general education. Confirm current official rules and product or employment details where relevant.
Frequently asked questions
Can net worth be negative?
Yes, when genuine outstanding liabilities exceed your current asset values.
Should I count my home?
You may include a reasonable current value, but include its outstanding mortgage as debt.
Do I count future income?
No. Future pay is not a present asset simply because you expect it.
Is a credit card limit an asset?
No. Unused borrowing capacity is not owned money; the amount actually owed is a liability.
How often should I recalculate?
Quarterly or annually is reasonable for tracking trends; use consistent dates and valuation methods.
Final checklist
-
[ ] Choose a valuation date and currency
-
[ ] List each asset once
-
[ ] Estimate present realistic values
-
[ ] List full outstanding debts
-
[ ] Subtract liabilities from assets
-
[ ] Cross-check equity treatment
-
[ ] Keep cash-flow and liquidity separate
-
[ ] Repeat consistently
Sources & Further Reading
-
US Securities and Exchange Commission / Investor.gov: Figure Out Your Finances — Net worth = assets less liabilities, tracked over time. Checked 27 October 2026.
-
Australian Securities and Investments Commission / Moneysmart: Net worth calculator — Asset and debt snapshot; estimates not predictions. Checked 27 October 2026.
Use the checklists as you go, and confirm the result before moving on to a more involved repair.